Swiss Franc Draws Global Investor Attention as Carry Trade Landscape Shifts
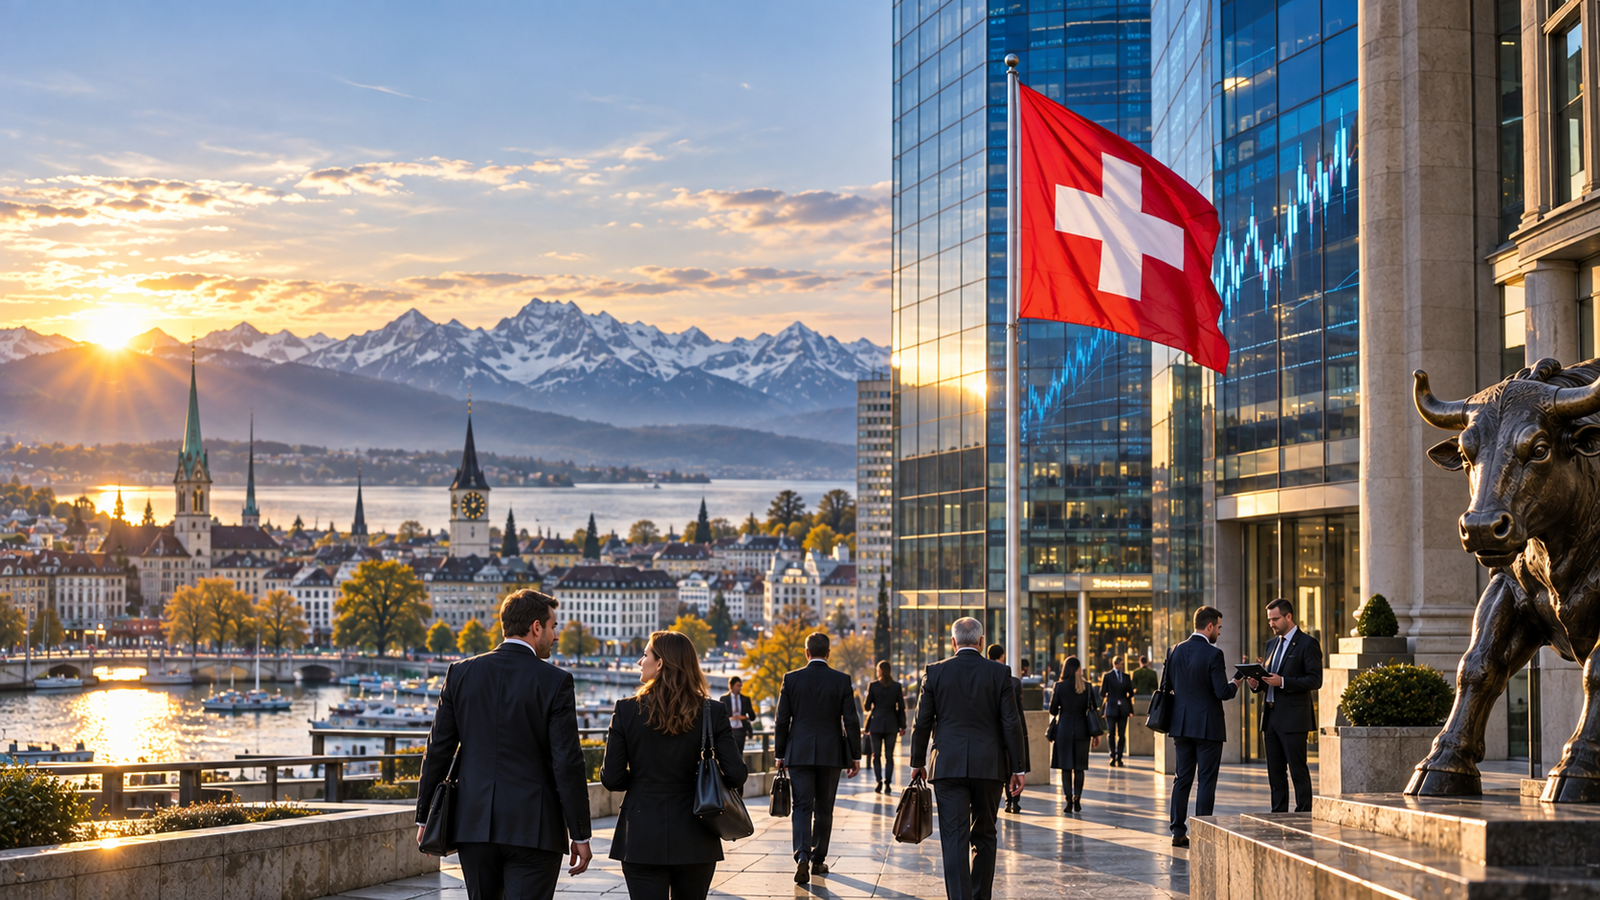
The Swiss franc is attracting renewed attention in global financial markets as investors reassess one of the world’s most widely used currency trading strategies. With interest rates in Japan moving higher and Switzerland maintaining one of the lowest policy rates among major economies, analysts say the franc is increasingly being viewed as a potential alternative funding currency for carry trades.
The development reflects a broader shift in international foreign-exchange markets, where investors are adjusting to changing monetary policies after years of relying heavily on the Japanese yen as the preferred source of low-cost funding.
A carry trade typically involves borrowing money in a currency with very low interest rates and investing the proceeds in assets or currencies that offer higher returns. Investors seek to profit from the difference between borrowing costs and investment yields. While the strategy can be lucrative during stable market conditions, it can also create significant losses if exchange rates move sharply against traders.
For decades, the Japanese yen occupied a central role in global carry trades because Japan maintained exceptionally low interest rates. That environment allowed investors to borrow cheaply and invest elsewhere. Recent policy changes by the Bank of Japan, however, have altered that dynamic.
Japanese authorities have gradually moved away from ultra-loose monetary settings, pushing interest rates to levels not seen in decades. Rising Japanese yields and efforts to support the yen have prompted investors to reconsider whether the currency remains the most attractive source of financing for carry trade positions.
Against that backdrop, attention has increasingly shifted toward Switzerland.
The Swiss National Bank currently maintains a key policy rate of 0%, creating conditions that make borrowing in francs comparatively inexpensive. Market participants note that the combination of low Swiss rates and deep financial markets makes the franc a practical candidate for funding global investment strategies.
Several investment firms and currency strategists have recently identified the franc as one of the most attractive alternatives to the yen. Some analysts argue that Switzerland’s monetary policy outlook differs significantly from Japan’s, with expectations that Swiss rates could remain low for an extended period while Japanese rates continue to normalize.
The appeal of the franc has already become visible in trading activity. Financial institutions and market observers have reported growing interest in franc-funded positions across currency and emerging-market investments. According to recent market commentary, some investors have reduced exposure to yen-funded trades while increasing the use of Swiss francs in search of more favorable carry opportunities.
Yet the growing popularity of the franc also introduces risks.
Unlike many currencies used in speculative trading strategies, the Swiss franc has long been viewed as a safe-haven asset. During periods of economic uncertainty, geopolitical tension, or financial-market stress, investors often move funds into Swiss assets. Such demand can strengthen the franc rapidly.
That characteristic creates a potential vulnerability for carry traders. If global investors borrow francs and the currency later appreciates sharply, the cost of repaying those loans rises. In extreme situations, investors may be forced to unwind positions quickly, triggering broader market volatility.
Financial history offers several examples of how such dynamics can affect markets. Carry trade reversals have contributed to sudden movements in currencies, bonds, and equities when investors rush to exit crowded positions. Analysts note that the risks become more significant when large numbers of market participants rely on the same funding currency.
Recent developments in Japan have reinforced those concerns. As the Bank of Japan raised interest rates and policymakers signaled a preference for a stronger currency, some carry trade positions faced pressure. Market participants have been closely watching whether those shifts could lead to a broader reallocation of global capital.
Currency strategists emphasize that the yen remains an important part of the global financial system despite recent changes. Japan’s financial markets remain among the world’s largest, and many investors continue to use the yen in funding strategies. Nevertheless, growing discussion around the Swiss franc highlights how quickly investor preferences can evolve when central-bank policies change.
For Switzerland, the trend presents both opportunities and challenges. A weaker franc can support exporters by making Swiss goods more competitive abroad, while increased international demand for Swiss financial products can strengthen the country’s role in global capital markets. At the same time, excessive currency volatility could complicate monetary policy and financial stability objectives.
The Swiss National Bank has historically monitored exchange-rate developments closely because currency movements can significantly affect inflation and economic growth. Any substantial increase in franc-funded carry trade activity could become an important factor for policymakers to watch in the months ahead.
Market participants now face a changing environment in which traditional assumptions about funding currencies are being challenged. The rise of the Swiss franc as a carry trade candidate illustrates how shifts in interest-rate policy can ripple across international markets and influence investment decisions far beyond national borders.
Whether the franc ultimately becomes the dominant alternative to the yen remains uncertain. What is clear is that investors are paying closer attention to Switzerland’s role in global currency markets as monetary policies continue to diverge among major economies. For now, the Swiss franc stands at the center of a growing debate about the future of one of finance’s most influential trading strategies.