Swiss Chocolate Industry Shows Signs of Recovery After Cocoa Price Shock
After two turbulent years marked by record cocoa prices, shrinking sales volumes, and pressure on consumers, Switzerland’s chocolate industry is beginning to see signs of stabilization.
Industry analysts and market participants say conditions have improved compared with the peak of the cocoa crisis that disrupted global chocolate markets in 2024 and 2025. While challenges remain, especially regarding future crop supplies and weather-related risks, recent data suggest the sector may be moving into a more favorable phase.
The recovery follows one of the most severe disruptions the chocolate business has experienced in decades. Cocoa prices surged to unprecedented levels after poor harvests in major producing countries, particularly in West Africa. Aging cocoa trees, crop diseases, and adverse weather conditions sharply reduced supply, while market speculation added further volatility. As a result, cocoa prices briefly climbed above historical norms by a wide margin, forcing manufacturers worldwide to adjust pricing and production strategies.
Swiss chocolate producers, known globally for premium brands and exports, were among the companies affected. Manufacturers passed a significant portion of higher ingredient costs on to consumers through price increases. Industry analysts estimate that leading chocolate makers raised prices substantially over the past two years in an effort to protect margins against soaring raw-material expenses.
The higher prices, however, came with consequences. Consumers in many markets reduced chocolate purchases or switched to lower-cost alternatives. According to industry figures, Swiss chocolate sales volumes declined in 2025, while exports also weakened. Revenue growth continued because of higher retail prices, but fewer products were sold overall. Domestic consumption likewise moved lower as households adjusted spending patterns in response to inflation and rising food costs.
Recent market indicators now point toward a gradual turnaround.
One of the strongest signals has come from cocoa prices themselves. Although cocoa remains more expensive than long-term historical averages, prices have fallen significantly from the extraordinary highs recorded during the crisis. Lower costs are easing pressure on manufacturers and improving the outlook for profitability throughout the supply chain.
Another encouraging development is the return of growth in cocoa processing activity. Global cocoa grindings, a widely watched measure of chocolate demand, increased during the second quarter of 2026 after several consecutive declines. Market observers view this as evidence that demand may be stabilizing after an extended period of weakness.
Major Swiss companies are also reporting more positive trends.
Barry Callebaut, one of the world’s largest chocolate and cocoa manufacturers, recently reported an increase in sales volume after two years of contraction. The company described improved customer demand and a healthier market environment compared with the conditions experienced during the height of the crisis.
Meanwhile, premium chocolatier Lindt & Sprüngli has continued to grow revenue despite ongoing pressure on sales volumes. Company executives have indicated optimism that volume growth could return as market conditions normalize and consumers adjust to the new pricing environment.
The broader global market is also adapting. Some manufacturers that previously reduced cocoa content or experimented with alternative formulations during the price spike are beginning to reconsider those strategies as ingredient costs moderate. Industry reports indicate that lower cocoa prices have improved the economics of producing traditional chocolate products again.
Despite the improving outlook, industry experts caution against assuming that volatility has disappeared.
The global cocoa supply chain remains heavily dependent on a small number of producing countries. Ivory Coast and Ghana alone account for a large share of worldwide cocoa production, making the market particularly vulnerable to weather disruptions, crop disease, and political or economic instability.
Meteorologists and agricultural analysts are closely monitoring the potential impact of El Niño conditions. Weather experts warn that unusually dry or hot conditions in West Africa could affect future harvests and create renewed supply pressures. Recent reports from Ivory Coast have already highlighted concerns among farmers regarding rainfall levels and crop development heading into the next production cycle.
At the same time, chocolate manufacturers are taking steps to reduce long-term supply risks. Companies are increasingly investing in sustainability programs, alternative sourcing regions, and agricultural support initiatives aimed at improving cocoa yields. Nestlé, for example, has expanded efforts to strengthen cocoa production in Brazil as part of a broader strategy to diversify supply sources beyond West Africa.
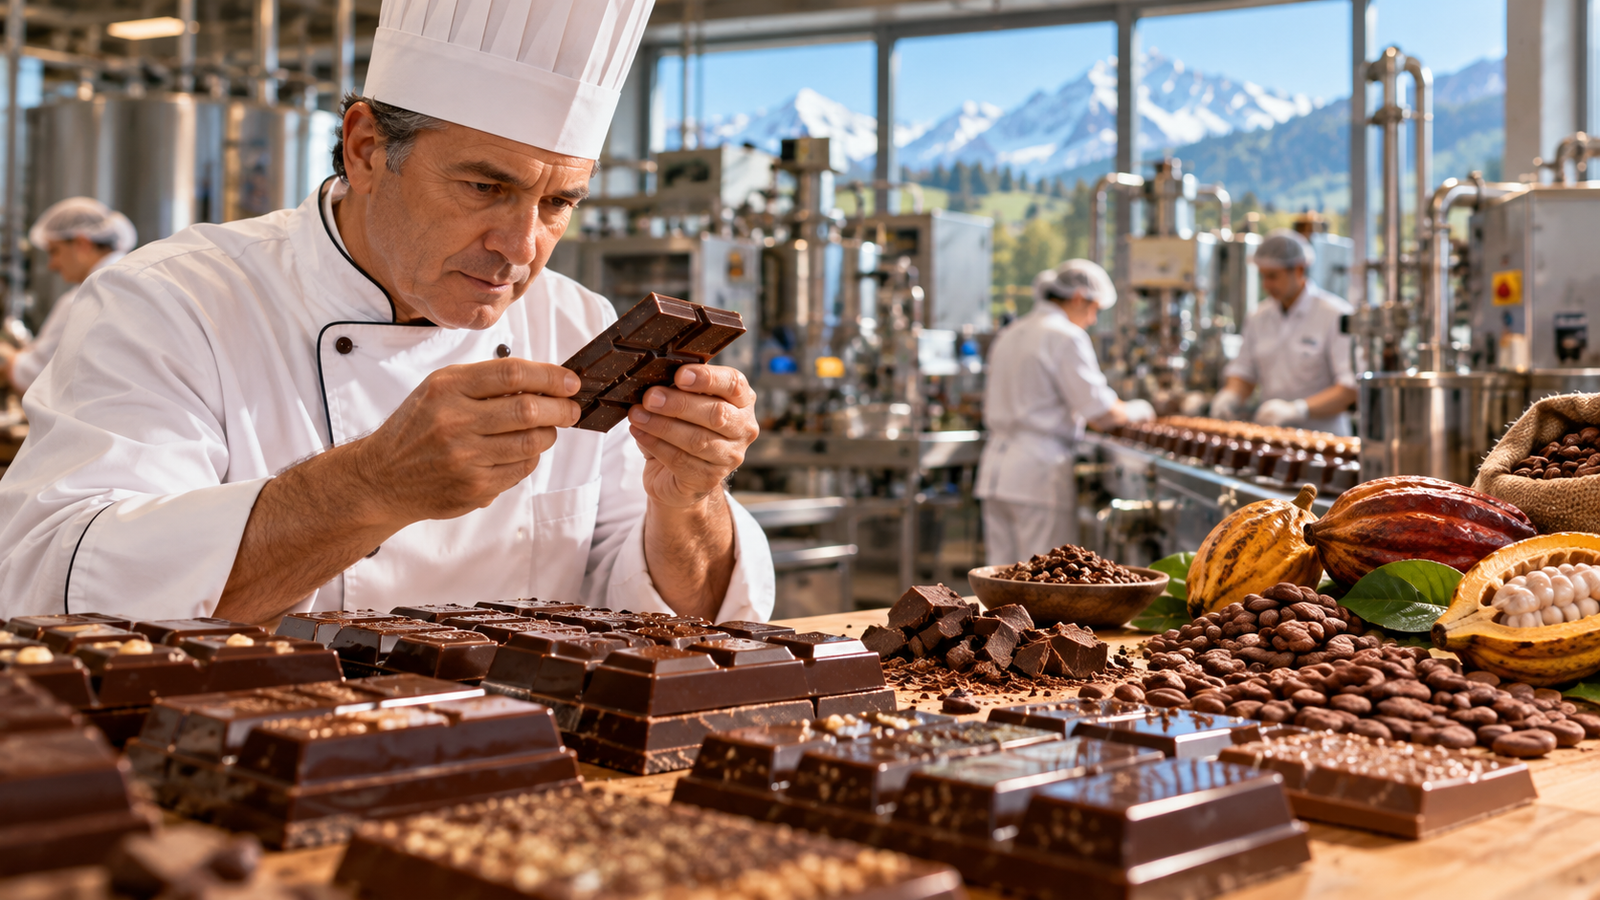
For Switzerland, where chocolate remains one of the country’s most recognized exports, the industry’s recovery carries importance beyond confectionery sales. Chocolate production supports manufacturing jobs, exports, tourism-related branding, and the international reputation of Swiss food products.
The latest indicators suggest that the industry’s most difficult period may have passed. Demand is showing signs of improvement, cocoa prices have retreated from historic highs, and leading manufacturers are reporting more encouraging results than they did a year ago.
However, the experience of the past two years has underscored how vulnerable the chocolate market remains to supply shocks originating thousands of miles away. While the outlook has brightened, industry leaders and analysts agree that cocoa markets are likely to remain sensitive to weather patterns and production risks for the foreseeable future.